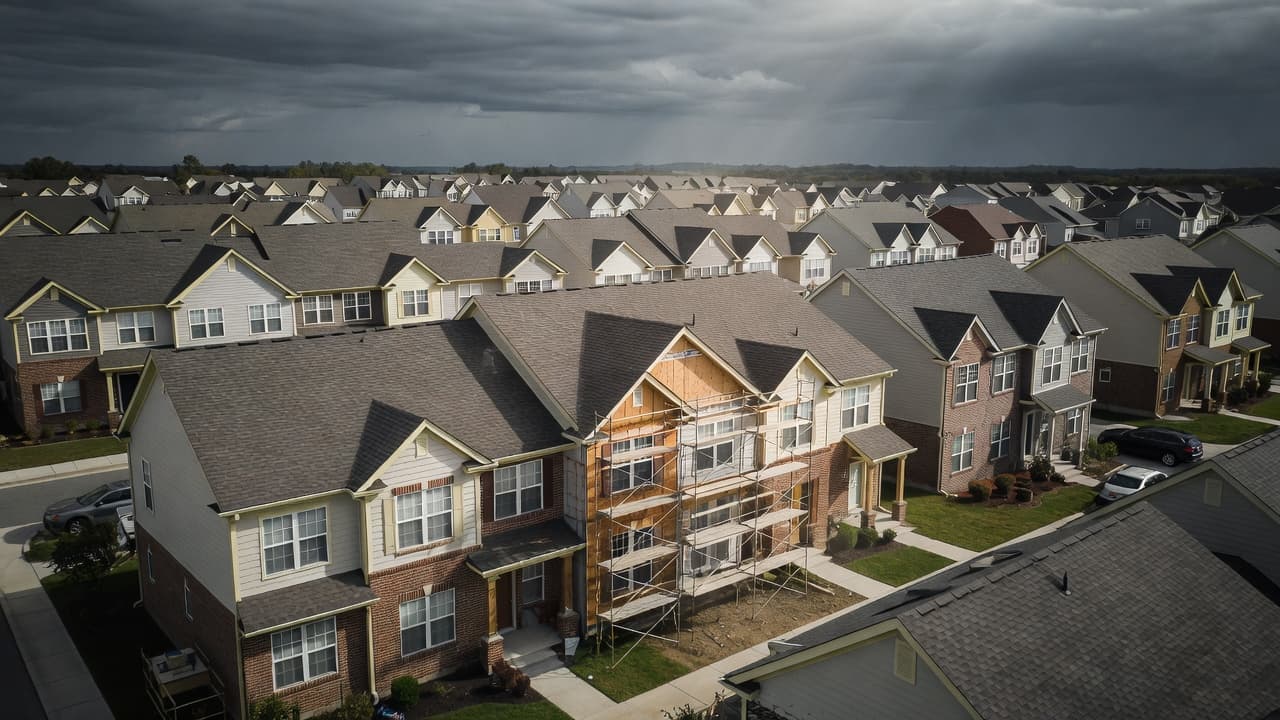
HOA Siding Replacement Plans for Multi-Building Communities
A siding project can look manageable until the first wall opens up. At that point, property managers and board members may suddenly face wet sheathing, missing kickout flashing, unbudgeted window repairs, and a construction schedule that disrupts hundreds of residents.
For condominium and townhome associations, HOA siding replacement is not merely a paint-color decision. It is a critical capital project that directly influences long-term property values, community curb appeal, and resident satisfaction. Managing these renovations requires a focus on legal, financial, and construction considerations.
The best projects start with a complete scope, a defensible funding plan, and a contractor who can manage the work building by building.
How should a condo board compare siding replacement proposals?
Compare condo siding replacement proposals against the same written building-envelope scope. A material name and total price do not show whether removal, concealed damage, flashing, trim, access and closeout are included. Resolve these differences before choosing a contractor.
Condo and HOA siding proposal comparison
Decision
What the board should request
Material and finish
Exact product, profile, color, finish, installation instructions and maintenance requirements.
Removal and hidden conditions
Included removal, inspection of exposed substrates, repair unit prices and approval limits.
Water-management details
Written treatment of flashing, openings, penetrations, roof-to-wall intersections and the water-resistive barrier.
Occupied-building logistics
Building phases, protected access, staging, parking, debris handling and resident notices.
Acceptance and warranty
Completion review, open-item tracking, product documentation and applicable written warranty terms.
Use this guide for planning. For the service scope and a property-specific bid request, visit condo and HOA siding replacement services. Coordinate roof-to-wall details with the roofing scope, and use the resident notice templates when communicating construction restrictions. Do not assume a roof-related insurance claim also pays for siding; the policy, documented damage and coverage decision control.
Key Takeaways
Proactive Assessment: Do not rely on visual cues alone; conduct a professional condition assessment that includes minor test removals to identify hidden damage to sheathing, flashing, and water-resistive barriers.
Standardized Scoping: Eliminate pricing discrepancies between bidders by creating a comprehensive, written project scope that details exact materials, repair unit prices for concealed conditions, and specific flashing requirements.
Envelope-First Approach: Treat siding as a building envelope project rather than a cosmetic upgrade, ensuring that critical water management components like kickout flashing and roof-to-wall intersections are prioritized to prevent moisture intrusion.
Financial and Resident Planning: Establish a robust funding plan that accounts for contingencies and market fluctuations, while maintaining clear, consistent communication with residents to manage disruptions during construction.
Start With a Community-Wide Condition Assessment
Replacing siding on one building simply because it looks weathered is a reactive measure. Replacing siding across a community without a professional condition assessment is expensive guesswork that often leads to significant deferred maintenance. Homeowners Associations should proactively identify failing systems before they become emergencies.
The board needs a clear picture of what is failing, where it is failing, and whether the visible siding is the primary source of the problem. Cracked panels, swelling trim, loose vinyl, peeling paint, and repeated water stains all deserve attention. These signs do not automatically mean every elevation needs a full replacement.
A qualified exterior contractor, building envelope consultant, or architect should perform a visual inspection of representative buildings and document the findings. The inspection should include walls with the heaviest weather exposure, roof to wall transitions, decks, patios, windows, doors, chimney chases, and utility penetrations.
For a multi-building community, the report should identify each building by address or building number. Broad statements, such as saying siding is near the end of its life, are not enough for board action or accurate bid comparison.
Document these conditions in the assessment:
Areas of deteriorated siding, trim, soffit, fascia, and general exterior maintenance needs
Soft, stained, delaminated, or otherwise damaged sheathing
Failed caulk joints around windows, doors, corners, and penetrations
Improper flashing at roofs, decks, ledger boards, windows, and doors
Signs of moisture intrusion, wood rot, insect damage, or mold
Buildings with different siding types, repair histories, or exposure conditions
A small test removal can answer questions that a visual inspection cannot. It may show whether housewrap is intact, whether the wall has a drainage gap, or whether the substrate can hold new cladding. That information belongs in the pre-bid scope.
If the bid assumes sound sheathing and the walls prove otherwise, the association has not received a fixed project price. It has received a starting number.
Review the association declaration, bylaws, rules, plat information, and maintenance matrix before the project scope is set. In many communities, the association maintains siding but owners remain responsible for limited components such as doors, windows, patios, or owner installed fixtures. Those boundaries need to be resolved before crews arrive.
Local building codes also matter. A siding replacement may trigger requirements for water resistive barriers, flashing, fastener schedules, ventilation details, or permits. Review governing documents, local code requirements, and reserve study recommendations with qualified legal, design, and construction professionals.
Define the Scope Before Asking Contractors for Prices
A contractor cannot price what the board has not defined. The result is usually a stack of contractor bids that look comparable but include different materials, different repairs, and different exclusions.
Build a written scope that applies to every bidder. It should state which buildings are included, whether all elevations are included, the approved siding profile, trim package, color selections, and the expected treatment of concealed damage. This document ensures that all siding contractors are providing quotes based on the exact same requirements.
For example, “replace siding as needed” is not a scope. A workable scope identifies the cladding system, substrate assumptions, flashing details, demolition requirements, and repair unit prices.
The document should answer practical job-site questions:
Will contractors remove existing siding or install over it where code permits?
Is new housewrap required on every exposed wall, or only where the existing barrier is damaged?
What flashing must be installed at windows, doors, roof intersections, deck ledgers, and penetrations?
How will damaged OSB, plywood, framing, and insulation be priced and approved?
Who removes and reinstalls lights, hose bibbs, address numbers, shutters, railings, cameras, and exterior outlets?
Are gutters, downspouts, roof edges, and landscaping included in the work?
The last point catches many boards off guard. Within multifamily communities, siding, roofing, gutters, and window flashing meet at the same wall plane. A contractor who replaces cladding but ignores roof-to-wall flashing can leave the original leak path in place.
Require unit prices for common concealed conditions. Typical units include sheathing by square foot, framing by lineal foot, insulation by square foot, and window or door flashing by opening. Unit pricing does not eliminate change orders, but it prevents every damaged panel from becoming a separate negotiation.
Use one written process for approving concealed-condition work. The contractor should provide photographs, location details, quantity, and proposed cost before covering the repair. Effective project management requires that the manager or designated board representative has authority limits in writing. Otherwise, a superintendent waits for answers while the schedule stalls.
Select Materials That Fit the Buildings, Budget, and Maintenance Plan
No siding material is entirely maintenance-free. Every product has specific installation rules, accessory requirements, weather limitations, and repair considerations that associations must evaluate.
Fiber cement siding, including popular brands like James Hardie, is common in association projects because it offers a consistent finish and broad trim options. These materials require correct clearances, proper fasteners, controlled cuts, and disciplined flashing. If fiber cement siding is installed tight to roofing, grade, or horizontal surfaces, it will absorb moisture at vulnerable edges.
Engineered wood products, including LP SmartSide, can work well when installed exactly to manufacturer requirements. The details matter, including ground clearance, edge sealing, flashing, fasteners, and paint maintenance. A board should not assume a wood-based product will tolerate deferred caulking and repainting.
Vinyl siding often has a lower installed cost and does not require painting. It can be an appropriate choice for certain townhome communities, but color matching after years of sun exposure can be difficult. Successful vinyl siding installations also require correct nail spacing and allowance for thermal movement. If panels are nailed too tight, they will buckle.
Metal panels may fit modern multifamily buildings or areas with severe impact exposure. They need careful detailing around openings and transitions, as they are not a shortcut around proper water management.
This comparison helps boards frame the discussion before final specifications are issued and ensures the chosen material aligns with community standards.
Material
Common strengths
Planning concerns
Fiber cement
Stable appearance, broad design options, noncombustible material
The material decision should match the long-term maintenance plan for the community, not a sales presentation. Ask for manufacturer installation instructions and warranty terms before approval. Confirm whether the selected installer meets any certification or credential requirements.
Visual consistency is equally important. A 40-building community can look patchy within a few years if the board permits multiple profiles, trim widths, corner treatments, and color substitutions. Set the approved siding product, color, exposure, trim style, soffit finish, and accessory colors in a board resolution or architectural standard.
Keep spare material from the project. Store labeled cartons of siding, trim, and accessories in a dry location if the association has storage space. Even a modest repair stock can save time when a future storm damages one wall.
Build a Funding Plan That Can Survive Field Conditions
The reserve study serves as a foundational planning tool, but it is not a definitive construction estimate. While it provides a useful replacement year and a target for your reserve funds, it cannot see behind walls or accurately account for current market fluctuations.
Start by comparing the reserve study assumptions against your formal condition assessment and current contractor pricing. If the reserve component is underfunded, the board must decide whether to phase the work, increase monthly contributions, secure a loan, levy a special assessment, or combine these strategies.
Do not set the project budget based solely on the lowest proposal. Your financial planning must include design or consulting fees, permit costs, diagnostic testing, temporary site protection, landscape restoration, a contingency fund, and any financing expenses. Your contingency budget should reflect the building age and known risk factors. For example, walls with visible water damage require a larger allowance than dry, recently built structures.
The board should also carefully weigh the project timeline. A full-community replacement may reduce unit costs and produce a more uniform result, but it creates a larger financial burden and more resident disruption in a single season. A phased plan lowers the immediate cost for the condo owners association, but it can increase total expenses over time and complicate color matching between phases.
There is no universal solution. The final decision should align with the association’s cash position, the current status of reserve funds, building conditions, and overall borrowing capacity.
A cheap bid with broad exclusions is not true budget control. It merely shifts uncertainty from the contractor’s proposal directly to the association’s balance sheet.
Require itemized bids categorized by building or phase. Proposals should clearly separate base siding work from allowances, alternates, and unit prices. They must also identify permit responsibilities, dumpster locations, site supervision, warranty terms, payment schedules, insurance limits, and expected crew size.
When reviewing contractor insurance certificates, do not stop at a surface-level check. You must ensure full insurance compliance by confirming general liability, workers compensation, automobile coverage, and umbrella coverage with the association’s professional insurance advisor. Always ask if subcontractors will be used and verify how their specific coverage is managed.
For large-scale projects, a construction attorney should review the final contract. The agreement must address change orders, payment timing, lien waivers, warranty response protocols, dispute procedures, site protection, and termination rights. Board minutes should clearly document why the board selected the chosen contractor, which alternatives were considered, and the formal process used to approve the funding.
Phase Construction to Limit Resident Disruption
Residents can tolerate noise and temporary access limits when the association provides accurate information. They become frustrated when crews appear without notice, parking disappears, and no one can answer basic questions.
A phased HOA siding replacement plan should group work by building, rather than by scattered walls throughout the community. Complete a building or a defined cluster before moving crews elsewhere. This reduces mobilization, keeps materials contained, and gives residents a clear start and finish window.
Before each phase begins, prioritize clear resident communication. Send notices by the communication methods allowed in the governing documents, such as email, portal notice, mailed letter, and posted notice. Give residents a realistic lead time, then send a short reminder before mobilization. Effective resident communication is vital for Homeowners Associations to maintain order and limit the impact of large scale renovations on daily living.
The notice should cover work dates, working hours, parking restrictions, access limits, noise expectations, pet precautions, balcony or patio clearing, window covering recommendations, and a project contact. It should also explain that dates can move because of weather or concealed repairs.
Some access issues require individual coordination. Residents may work from home, need accessible parking, have medical equipment near exterior outlets, or keep pets that react badly to construction activity. The manager should collect those requests early. The contractor cannot solve a special access issue after scaffolding is in place.
Daily site control matters. Crews should secure ladders, keep paths clear, protect windows and landscaping, manage nails with magnetic sweepers, and remove loose debris before leaving. A clean site is not just cosmetic. It limits injuries, complaints, vehicle damage claims, and fire risk.
Require a designated superintendent who can make field decisions and communicate with the manager. The board should not become the contractor’s daily dispatch office. One point of contact prevents contradictory instructions and keeps the project record clean.
Treat Flashing, Housewrap, and Sheathing as Part of the Siding Work
Siding is the visible layer, but water management behind the cladding determines whether the wall assembly stays dry. Protecting the building envelope is critical to long-term performance.
Every siding replacement scope should identify how the contractor will inspect and repair water-resistive barriers, window flashing, kickout flashing, and roof-to-wall intersections. These hidden details are easy to overlook during initial assessments and expensive to revisit once the project is underway.
Kickout flashing is a frequent trouble spot. It sits where a roof edge ends against a sidewall and directs water into a gutter. When this component is missing, roof runoff can dump behind the siding, causing significant moisture intrusion that soaks the wall cavity. Replacing siding without correcting that condition is essentially a failed repair.
Window and door details need equal attention. The flashing sequence must direct water outward rather than trapping it behind tape or trim. Existing windows may have limited flashing, damaged nailing fins, or failed sealants. The contractor should photograph these conditions before installing new cladding to ensure a complete record.
Sheathing repairs need clear standards. Some damage is limited to a small section around a failed penetration, but if left unaddressed, moisture exposure can lead to extensive structural damage that extends into framing, insulation, or interior finishes. The board needs a defined escalation process for when repairs exceed the unit-price allowance or reveal deeper structural concerns.
Do not accept a blanket instruction to replace rotten wood as needed. Ask how the contractor identifies rot, who verifies the quantity, and what documentation supports the change order. A photo without an address, elevation, or measurement is weak project documentation.
The project team should inspect representative walls before they are covered. For larger communities, consider a pre-construction mockup or a first-building review. Confirm siding layout, trim details, flashing, fastener placement, caulk joints, and finished appearance before the same work repeats across twenty buildings.
Keep a Board Record That Holds Up Later
Boards change and managers rotate. Ten years after a siding replacement project, a future board member may ask why Building 14 required new sheathing, why the exterior color was changed, or whether a contractor warranty remains active.
Create a comprehensive project file that includes the condition assessment, reserve study excerpts, board resolutions, meeting minutes, bids, contracts, certificates of insurance, permits, product data, color approvals, payment applications, change orders, inspection reports, photographs, lien waivers, and warranty documents.
Minutes should record the final decision rather than every individual discussion. Clearly state the motion, the board vote, the selected contractor, the approved amount, the specific funding source, contract authority, and any owner notice requirements. If the board rejects a lower bid due to an incomplete scope of work, weak supervision, poor references, or specific exclusions, record the basis for that decision in the official files.
A final closeout package should include a building by building completion list and a punch list record. Confirm that debris is removed, gutters are reinstalled where required, damaged landscaping is addressed, and all exterior accessories are back in their original places.
Walk the finished work with the contractor before issuing the final payment. Check transitions, caulk joints, trim alignment, exposed fasteners, flashing, siding clearances, downspout locations, and any visible damage. Hold retainage if the contract allows until all punch list work is complete.
Frequently Asked Questions
Can we just replace the siding without addressing the sheathing or flashing?
No, replacing siding without addressing the underlying building envelope is often a wasted investment. Damaged sheathing or improper flashing will continue to allow water intrusion, potentially leading to rot and mold behind the new cladding.
Why do we need unit pricing for concealed conditions?
Unit pricing allows the board to establish pre-approved rates for repairs that cannot be identified until the old siding is removed, such as rotted framing or damaged OSB. This prevents every instance of concealed damage from requiring a new, time-consuming contract negotiation.
How should we handle resident disruption during the project?
Phasing the construction building-by-building rather than scattered across the property allows for a clear, predictable schedule. Providing consistent, advance notice through established communication channels helps residents prepare for noise, limited access, and parking changes.
Should the board always choose the lowest bid?
Not necessarily, as low bids often include broad exclusions or lack critical requirements that lead to expensive change orders later. A professional, detailed bid that accounts for the specific needs of the association is typically more cost-effective and provides better budget control than a low-cost, vague proposal.
A Controlled Siding Project Protects More Than Appearance
A multi-building siding project succeeds when the board treats it as a building envelope program rather than a simple cosmetic upgrade. The work must address the wall behind the cladding, the budget behind the contract, and the residents living beside the job site.
The strongest HOA siding replacement plans rely on a complete scope, consistent materials, documented decisions, and disciplined field inspection. By following this structured approach, an association protects its assets and financial health while avoiding the common pitfall of paying twice for the same wall. Ultimately, a well-managed HOA siding replacement program ensures the long-term value and structural integrity of the entire community.
Does HOA Insurance Cover Roof Replacement? A 2026 Guide for Boards & Property Managers
Short answer: An HOA’s master insurance policy usually covers roof replacement when the damage comes from a sudden, covered peril — most often hail or wind — but it does not cover a roof that has simply worn out from age. Whether a claim is paid almost always comes down to one distinction: sudden accidental damage versus gradual deterioration.
That single line is what every board and property manager needs to understand before they file — or before they assume they’re stuck funding a roof out of reserves. Below is how coverage actually works on HOA, condo, and townhome roofs, why valid claims get underpaid, and what’s specific to associations here in the Upper Midwest.
Covered peril vs. wear-and-tear: the distinction that decides everything
Property insurance pays for damage that happens suddenly and accidentally. It does not pay for the slow decline of a building component that has reached the end of its service life. A roof is a maintenance item, so insurers scrutinize roof claims closely to separate storm damage from age.
Does HOA Insurance Cover Roof Replacement? A 2026 Guide for Boards & Property Managers 1
Situation
Typically covered?
Hail bruising or fractured shingle mats from a storm
Yes — covered peril
Wind that lifts, creases, or tears off shingles
Yes — covered peril
Tree or debris impact during a storm
Yes — covered peril
Sudden water intrusion from storm-created openings
Usually — covered peril
22-year-old shingle roof that is curling and granule-bald
No — wear and tear / age
Leaks from deferred maintenance or poor prior installation
No — maintenance exclusion
Ice-dam damage
Sometimes — depends on policy language
The practical takeaway: a roof can be old and have a valid claim. Age alone doesn’t void coverage. If a documented hail or wind event caused functional damage, the age of the roof affects depreciation — not whether the loss is covered.
What the HOA master policy covers — and what it doesn’t
Most associations carry a master (blanket) property policy that covers the buildings, including roofs, on a replacement-cost or actual-cash-value basis. What it covers in practice depends on three things:
The peril. Named-peril policies cover only listed causes; “special form” (open-peril) policies cover everything except stated exclusions. Most master policies that cover roofs are special form.
The valuation. Replacement Cost Value (RCV) pays to replace the roof at today’s prices; Actual Cash Value (ACV) pays replacement cost minus depreciation, which on an older roof can be a large gap.
The deductible. Wind and hail deductibles on association policies are frequently percentage-based (commonly 1%–5% of the insured building value), not a flat dollar amount — which can mean a five-figure deductible per building on a large complex.
What master policies generally exclude: ordinary wear, deterioration, maintenance failures, and — critically — the cost gap created by depreciation on an ACV policy.
Who pays: the association vs. the individual owner
For condos and townhomes, “who pays for the roof” depends on the governing documents and the policy structure. The roof is almost always part of the common elements, which means it’s the association’s responsibility and runs through the master policy — not an individual owner’s HO-6 unit policy. Owners typically can’t file their own claim for a common-element roof.
Does HOA Insurance Cover Roof Replacement? A 2026 Guide for Boards & Property Managers 2
Two costs still tend to land on the association, and sometimes get passed to owners through assessments:
The deductible. A percentage-based wind/hail deductible can be substantial, and your declarations and bylaws determine who absorbs it.
Depreciation under ACV. If the policy pays ACV and the roof is older, the difference between the check and the actual replacement cost has to come from somewhere — usually reserves or a special assessment. See our HOA roof replacement cost guide for what Minnesota boards are actually budgeting in 2026.
This is exactly why getting the claim documented and scoped correctly matters so much: it directly affects how big that gap is.
Why valid HOA roof claims get denied or underpaid — and how to prevent it
Plenty of legitimate association claims are denied or paid far below the real cost of replacement. The most common reasons:
Under-documented damage. A quick adjuster walk that misses hail bruising on the back slopes or test squares that weren’t pulled. If it isn’t documented, it isn’t paid.
No storm verification. Carriers check whether a qualifying hail or wind event actually hit your coordinates on the date claimed. Without data tying the damage to a specific event, the claim stalls. Our storm intel tool ties NWS hail and wind reports to your address.
Scope written too low. The initial estimate omits code-required upgrades, proper flashing, drip edge, or full-system items, leaving the association short at the worst possible moment.
Matching ignored. When only some buildings or slopes are damaged but the replacement material won’t reasonably match the undamaged sections, the scope often needs to be supplemented.
The fix is documentation discipline: photographed test squares, NOAA storm-event data tied to your address and date, an estimate written to carrier format, and supplements filed when the first scope is light. That’s claim management, not “storm chasing” — and it’s the difference between a paid roof and a special assessment.
What’s specific to HOAs in Minnesota and the Upper Midwest
Associations in MN, WI, IA, ND, and SD sit in one of the most hail-active regions in the country, which shapes how these claims play out:
Frequent qualifying events. The Upper Midwest sees heavy hail and straight-line wind seasons, so multi-building complexes often have legitimate, documentable losses — sometimes across several roofs at once.
Matching rules. Minnesota has consumer-favorable “matching” provisions for property insurance that can require an insurer to fund a reasonably uniform appearance when damaged materials can’t be matched to undamaged ones. How it applies to your specific roof and policy is fact-dependent — confirm it with your agent or attorney.
Claim time limits. Policies include deadlines for reporting damage and for filing suit (often a couple of years), so boards should not sit on suspected storm damage waiting to “see if it leaks.” Document and assess promptly.
Governing-document interplay. State common-interest-ownership law and your bylaws determine the deductible and assessment mechanics — read them before a loss, not after.
Treat the specifics above as general information, not legal or insurance advice; your declarations page, bylaws, and a licensed adjuster or attorney govern your actual situation.
The claim process for an HOA roof, in brief
Image placeholder: phased-apartment-reroof-multifamily.jpg — to be replaced with real photo.
Document the event — date, NOAA storm data for your location, and a photographed roof inspection with test squares.
File and request an adjuster meeting — your roofing contractor should be on the roof with the carrier’s adjuster, not waiting in the parking lot.
Scope to carrier format — an estimate written in the format adjusters use (e.g., Xactimate) reduces friction and disputes.
Supplement when needed — when the initial scope misses code items or full-system requirements, file a supplement with documentation.
Phase the work — multi-building associations get a phased schedule so owners know exactly when each building is active, and resident notice templates keep owners informed as crews move through the community.
If your association’s roof may have storm damage, our insurance-claim process walks through documentation, adjuster meetings, and supplements step by step — and a free assessment tells you whether you have a claim worth filing before you commit to anything. Boards who manage multiple buildings should also see our HOA roofing services overview.
Frequently asked questions
Does HOA insurance cover an old or worn-out roof?
Not for age-related wear. If an old roof is damaged by a covered peril like hail or wind, the loss can still be covered, but the roof’s age affects depreciation — and on an actual-cash-value policy that can create a significant gap between the claim payment and the real replacement cost.
Who pays the deductible on an HOA roof claim?
The association is generally responsible for the master-policy deductible, which for wind and hail is often a percentage of the insured value rather than a flat amount. Whether and how it’s passed to owners depends on your bylaws and declarations.
Can a unit owner file their own claim for the roof?
Usually not. On condos and townhomes the roof is typically a common element covered under the association’s master policy, so the claim runs through the HOA, not an individual HO-6 policy.
Can the HOA be required to replace undamaged roofs to match?
Sometimes. When damaged materials can’t be reasonably matched to adjacent undamaged sections, “matching” provisions may require the scope to fund a uniform appearance. This is fact- and state-specific, so confirm how it applies to your policy.
How long does an HOA have to file a storm-damage roof claim?
Policies set their own reporting and suit-limitation deadlines, often around two years, and the clock can start at the date of loss. Boards should document and assess suspected damage promptly rather than waiting for leaks.
What if the insurance adjuster’s estimate is too low?
A low initial scope can be supplemented. With photographed damage, storm-event data, and an estimate written to the carrier’s format, missing code items and full-system costs can be added before the association is left short.
This article is general information for HOA boards and property managers and is not legal, financial, or insurance advice. Your policy declarations, governing documents, and a licensed professional govern your specific situation.
Written by the HOA Roofing Pro team — HOA, condo, and multifamily roofing and insurance-claim specialists serving MN, WI, IA, ND, and SD.
Multi-Family Roof Replacement Process: From Bid to Punch List (MN)
A multi-family roof replacement — apartment, condo, or townhome community — takes 3 to 8 weeks of active work, but the full process from initial inspection through final lien waiver typically runs 4 to 9 months in Minnesota. Property managers and HOA boards who treat this like a residential reroof get burned on scheduling, tenant communication, code compliance, and warranty paperwork. This is how an experienced multifamily roofing contractor actually runs the job.
Phase 1: Pre-Bid (Weeks 0-4)
Drone & Walk Inspection
A real multifamily roofer doesn’t price from Google Maps. We deploy drone roof reports plus a physical walk on every building, IR thermal scans on flat roofs to find wet insulation, and core cuts on suspect areas. Photos and condition notes go into the bid package.
Building-by-Building Takeoff
Each building gets its own line item: square footage, slope, deck type, ventilation count, penetrations, drain count for flat roofs. This is what separates a real multifamily bid from a residential outfit pretending they can scale.
System Recommendation
Based on building type:
2-3 story townhomes: Architectural shingle (Class 4 hail-rated if hail history) or standing seam metal panel for low-pitch sections
3-4 story garden-style apartments: TPO single-ply (60-80 mil) on flat sections, architectural shingle on mansards and visible slopes
Mid-rise condos: TPO, modified bitumen 2-ply, or EPDM depending on roof drainage and parapet conditions
Townhome roofs with cathedral attic insulation: ventilation upgrade is mandatory or the new shingles will void warranty in 8-10 years
Bid Package Delivery
HOA Roofing Pro delivers a board-ready package: drone photos, takeoff, three pricing options (good/better/best), unit pricing for decking and ventilation, warranty paperwork, insurance certificates, references. Typical lead time: 7-10 business days from site visit.
Phase 2: Board Approval / PM Sign-Off (Weeks 4-8)
For HOA-owned properties, the bid goes through a board vote — see our HOA board vote process guide. For institutional apartment owners or property management companies, sign-off depends on the asset manager and capital budget approval cycle.
This is where most multifamily projects stall. Common delay sources:
Reserve study update needed before special assessment vote
Owner vote required by bylaws for assessment over threshold
Capital approval process at the institutional owner level
Phase 3: Pre-Construction (Weeks 8-12)
Contract Execution
Signed contract names the association/owner as additional insured, includes manufacturer warranty registration, lien waivers schedule, payment schedule (typically: 0% deposit, progress payments tied to phase completion, final 10% retainage on punch list signoff).
Material Order
Lead times in 2026:
Standard architectural shingle: 2-3 weeks
Class 4 impact-rated shingle: 3-5 weeks (some colors longer)
TPO 60 mil white: 2-4 weeks
TPO specialty colors (tan, gray): 4-6 weeks
Standing seam panels: 4-8 weeks (custom fab)
Custom metal flashing: 2-3 weeks
Permits
Each Minnesota municipality requires a permit for roof replacement on multifamily. Larger cities (Minneapolis, St. Paul, Edina, Plymouth, Bloomington) require commercial permit with engineer stamp on uplift calculations for low-slope assemblies. Typical permit lead time: 5-15 business days.
Tenant / Owner Communication
Two notices minimum:
2 weeks before start: Project scope, schedule, contractor name and emergency contact, parking impacts, debris management
48 hours before each building: Specific start day, expected noise hours, deck patio / patio furniture instructions, vehicle relocation
HOA Roofing Pro drafts both notices for the board / property manager — bilingual (English/Spanish) on request.
Phase 4: Active Construction (Weeks 12-18)
Daily Process
For a 50-unit townhome community with 4 buildings:
Day 1 (per building): Tarp protection of landscaping, gutters, AC units, patios. Tear-off starts. Dumpsters staged.
Day 2: Tear-off completes. Deck inspection. Damaged sheathing replaced (per unit price). Ice-and-water shield to MN code at all eaves, valleys, penetrations. Synthetic underlayment installs.
Day 3-4: Shingle install. Drip edge, valleys, ridge ventilation. Step flashing at all sidewalls.
Day 5: Cleanup with magnetic sweep, gutter clear, debris haul, final site check.
Multiply by building count — typical pace: 1 building every 4-7 days weather permitting.
For TPO / Low-Slope Buildings
Slower pace due to mechanical fastening or fully-adhered installation, hot-air welding of seams, flashing fabrication. Expect 7-12 days per 10,000 sf roof section.
Safety & Code Compliance
Fall protection: full personal fall arrest above 6′ (OSHA 1926.501)
Warning line systems on flat roofs over 50′ from edge
Crane / boom lift operations with certified operators
Daily site safety meeting documented
Workers’ comp and GL certificates on file with property manager
Communication During Construction
HOA Roofing Pro assigns a project manager who provides:
Weekly progress email to board / PM with photos
24-hour emergency contact for water intrusion or owner complaints
Daily on-site superintendent who’s the single point of contact
Change order documentation BEFORE work proceeds — no surprise invoices
Phase 5: Punch List & Closeout (Weeks 18-20)
Walk-Through
Property manager / board representative walks every building with the project manager. Document:
Any landscaping damage requiring restoration
Gutter damage or paint scratches
Penetration sealants reviewed
Attic ventilation final count
Cleanup completeness
Warranty Registration
Manufacturer warranty (GAF Golden Pledge, Carlisle Total Roof, Owens Corning Platinum, etc.) registered with manufacturer within 30 days of completion. Workmanship warranty issued by contractor (typical: 10-25 years for multifamily). Both delivered to association in PDF and physical hard copy.
Final Documentation Package
As-built drawings (especially for low-slope assemblies)
Material data sheets and manufacturer certificates
Final lien waiver from contractor and all major suppliers
Photos of completed work — every building, every angle
Final Payment
10% retainage released after punch list signoff and final document delivery. This is the contract enforcement leverage — never release retainage before warranty paperwork is in hand.
Phase 6: Post-Closeout (Months 6-12)
6-Month Inspection
HOA Roofing Pro returns at 6 months and 12 months to inspect critical penetrations, sealant condition, attic moisture (for ventilation upgrades), and tenant-reported leaks. This catches workmanship issues before they become warranty disputes.
Annual Maintenance
For flat-roof buildings, twice-annual gutter clearing, drain inspection, and penetration check is included in extended workmanship warranties. For shingle roofs, annual visual inspection after major hail or wind events.
Common Multi-Family Project Failures
Residential contractor scales up — runs out of crew capacity, schedule slips 4-8 weeks
No drone / no per-building takeoff — change orders 15-30% over contract
Ventilation overlooked — new shingles fail at 8-10 years instead of 22-30
Tenant communication failure — board fields 50 angry calls in week 1
Warranty paperwork never registered — discovered at year 8 when there’s a leak
Code compliance shortcuts — ice-and-water shield only to drip edge, not warm wall
Insurance certificate doesn’t name HOA — association exposed if worker injured
How HOA Roofing Pro Runs Multifamily
We’ve built our entire operating model around multi-family work:
Dedicated multifamily project manager (not the same person doing your driveway-repair neighbor)
Crew capacity sized for 8-16 buildings per active project
Union or open-shop labor depending on owner preference and prevailing wage requirements
Direct accounts with GAF, Carlisle, Owens Corning, Atlas, IKO for material allocation in peak season
Drone roof reports on every bid — no exceptions
Board attendance at meetings before and during project
Parent company Sellers Roofing Company provides 30+ years of MN multifamily experience and bonding capacity
Frequently Asked Questions
How long does a multi-family roof replacement actually take?
For a 4-building, 50-unit townhome community: 4-6 weeks active construction, 4-9 months including bid, approval, and closeout. For a single 3-story apartment building with TPO: 2-4 weeks active.
Can tenants stay during construction?
Yes. Tenants remain in their units. Active work is daytime (7am-5pm typical). Tarp protection covers patios, vehicles relocated during direct overhead work.
What if it rains during a tear-off?
Standard practice: tear off and dry-in (felt + ice-and-water) the same day. Forecast monitored hourly. If active rain hits during tear-off, crew dries in immediately and resumes shingle install next clear day.
Do we need engineering calcs?
For low-slope (TPO, EPDM, modified bitumen) on buildings over 2 stories in most MN cities, yes — uplift calcs stamped by a licensed engineer are required for permit. HOA Roofing Pro coordinates this with our in-house engineer relationships.
Ready to plan your multi-family roof replacement? Call (651) 627-5270 or request a board-ready bid. Free drone inspection, 7-10 business day turnaround on full bid package.
How HOA Boards Vote on Roof Replacement: Process, Quorum & Bid Approval
Most Minnesota HOA boards can approve a roof replacement with a simple majority vote of the board of directors — no homeowner vote required — when the project is a like-for-like replacement of an existing capital asset funded from reserves or insurance proceeds. A full homeowner vote is usually only triggered when the board needs a special assessment that exceeds bylaw limits, when material is being upgraded beyond original spec, or when reserves are insufficient.
This guide walks board members through the actual process: from receiving bids, to noticing the meeting, to recording the vote, to executing the contract — and where most boards make procedural mistakes that get challenged later by an owner who didn’t like the assessment.
Step 1: Establish the Need (Documentation)
Before a vote, the board needs documented evidence that replacement (not repair) is justified. This usually means:
Reserve study showing roof at or past expected life (typical: shingle 22-30 yr, TPO 20-25 yr, EPDM 25-30 yr in Minnesota climate)
Recent inspection report from a licensed roofer documenting active leaks, granular loss, blistering, deck deflection, or storm damage
HOA Roofing Pro provides a free drone roof report with photos, IR thermal imaging, and a written condition assessment as part of every bid. Request a board-ready bid.
Step 2: Solicit Bids (Minimum Three)
Best practice — and required in many MN HOA bylaws — is three written bids from licensed, insured, bonded contractors. For an HOA project specifically, the right bidders should:
Hold MN Residential Roofing License (BC license) for townhomes/condos, or commercial license for apartment buildings
Carry $2M+ general liability and workers’ comp covering union or open-shop labor
Demonstrate multifamily/HOA experience — not just residential
Provide per-building line items and unit pricing for decking, fascia, ventilation
Include manufacturer warranty paperwork (GAF Golden Pledge, Carlisle Total Roof, etc.)
Red flag: A “bid” that’s a one-page total with no per-building breakdown. The board needs detail to defend the vote.
Step 3: Bid Comparison Worksheet
The board should compare bids on these axes — not just price:
Comparison Item
Bidder A
Bidder B
Bidder C
Total contract price
Price per square foot installed
Decking allowance (sheets included)
Unit price for extra decking
Shingle class (Class 3 vs Class 4 hail)
Underlayment (synthetic vs felt)
Ice-and-water coverage area
Ventilation upgrade included
Manufacturer warranty length
Workmanship warranty length
Insurance limits (GL / WC / umbrella)
Union or open-shop labor
Schedule (start / completion)
Payment schedule
References (3 HOA projects last 24 mo)
Step 4: Notice the Board Meeting
Minnesota Common Interest Ownership Act (MCIOA, MN Stat. §515B) requires the board to provide notice of any meeting where the board will vote on a contract over a certain threshold (often $25,000 or 5% of annual budget in bylaws). Notice requirements typically include:
Mailed or emailed notice to all homeowners 10-30 days before the meeting (check your bylaws)
Posted notice on the community board / website
Agenda listing the roof replacement vote as an action item
Copies of bids and bid comparison worksheet available for owner review
Step 5: The Vote Itself
Board-Only Vote (Most Common)
For routine replacement of a capital asset from reserve funds or insurance proceeds, a simple majority of the board of directors typically approves the contract. Quorum is usually a majority of seated directors. The motion should specify:
Selected contractor name and contract amount
Funding source (reserves, insurance, special assessment)
Authorized signer (usually board president and treasurer)
Project start window
Owner Vote (When Required)
An owner vote is generally required when:
Special assessment exceeds bylaw limit (often 10-20% of annual dues)
Project includes a material upgrade beyond original spec (e.g., switching from shingle to metal)
Reserves are insufficient and the board needs to borrow against assets
Owner vote thresholds vary — typical: 51% of all units (not just those present), measured by ownership interest. Bylaws control.
Step 6: Record the Vote
Minutes must reflect:
Date, time, location of meeting
Directors present and absent
Quorum established
Motion text (verbatim is safest)
Vote tally (X yes, X no, X abstain) by name
Any owner comments offered during the open portion
Boards get sued for vote validity more often than for the underlying decision. Tight minutes are the best defense.
Step 7: Execute the Contract
Before signing:
Confirm contractor’s license, insurance certificate naming the HOA as additional insured
Confirm manufacturer warranty registration form is in the contract
Confirm lien waivers (partial and final) are part of the payment schedule
Confirm performance and payment bond if contract over $100K (some bylaws require)
Voting without three bids — challenged later as failure of fiduciary duty
Insufficient owner notice — voids the contract in some jurisdictions
No documented bid comparison — looks like board picked their friend
Skipping reserve study — opens door to “premature replacement” challenges
Not naming HOA on insurance certificate — leaves association exposed
Approving “allowance” decking without unit price — guaranteed change-order fight
How HOA Roofing Pro Supports Board Votes
We provide every HOA board with:
Board-ready bid package — formatted exactly for board distribution
Side-by-side bid comparison worksheet (so your board can compare us against others fairly)
Sample motion language and minutes language
Pre-vote board call with our estimator — Q&A with directors before the vote
Insurance certificate naming your HOA as additional insured before contract signing
Lien waivers at each payment milestone
Frequently Asked Questions
Do all board members have to vote in person?
No. Most MN HOA bylaws allow electronic participation and written/electronic consent. Some require physical quorum for capital expenditures — check your bylaws.
Can a board approve a roof replacement without an owner vote?
Yes, when funded from reserves or insurance proceeds and the project is like-for-like replacement of an existing capital asset. Owner vote is typically triggered only by special assessments above bylaw limits.
What if an owner challenges the vote?
Tight minutes, three documented bids, proper notice, and a clear paper trail of the bid comparison protect the board. The MN Common Interest Ownership Act gives boards broad authority for capital maintenance.
How long from vote to project start?
Typically 3-8 weeks after contract signing, depending on weather, materials lead time, and contractor schedule. Class 4 shingles and specialty TPO colors can have 4-6 week lead times.
Need a board-ready bid package? Call (651) 627-5270 or request a quote. We’ll attend your board meeting at no charge to answer director questions before the vote.
HOA Roof Replacement Cost Guide: What MN Boards Pay in 2026
HOA roof replacement in Minnesota typically runs $8 to $18 per square foot installed in 2026, with most associations budgeting $280,000 to $1.4M for a full multi-building roof replacement. The real number depends on roof type (shingle vs. TPO vs. standing seam), building height, deck condition, code upgrades, and whether you bid it through a board-friendly contractor or a residential outfit pretending to do multifamily.
This guide walks HOA boards, condo associations, and apartment property managers through real cost ranges — line by line — and shows how an experienced HOA roofing contractor like HOA Roofing Pro structures a replacement bid that survives a board vote and an insurance review.
Average HOA Roof Replacement Cost (2026 Minnesota)
Roof Type
Cost Per Square Foot Installed
Typical 25-Unit Building
Typical Townhome Community (50 units)
Architectural shingle (Class 4 hail)
$7.50 – $11.00
$95K – $140K
$320K – $520K
Architectural shingle (standard)
$6.50 – $9.50
$80K – $120K
$280K – $450K
TPO single-ply (60 mil)
$9.00 – $14.50
$115K – $185K
$380K – $640K
EPDM (60 mil mech. attached)
$8.50 – $13.00
$105K – $165K
$350K – $580K
Modified bitumen (2-ply SBS)
$11.00 – $17.00
$140K – $215K
$480K – $780K
Standing seam metal (24 ga)
$14.00 – $22.00
$180K – $280K
$620K – $1.05M
Ranges assume Twin Cities metro labor, full tear-off, code-compliant decking replacement at 5-10%, and union prevailing wage where applicable. Add 8-15% for buildings over 3 stories.
What Drives HOA Roof Cost
1. Roof System Choice
Steep-slope buildings (most townhomes and 3-story condos) use architectural shingle or, increasingly, standing seam metal on low-pitch roofs. Flat or low-slope apartment buildings run TPO, EPDM, or modified bitumen. Class 4 impact-rated shingles cost $1.00-$1.50/sf more but typically earn a 15-30% homeowner insurance discount in Minnesota — pays back in 4-7 years.
2. Deck Condition
Plan-check shows OSB or plank decking. Hidden rot from years of ice dam leaks is the #1 budget surprise. Reputable HOA bids include a per-sheet unit price ($95-$140/sheet 4×8 OSB installed) so the board sees the math instead of a vague “extras may apply” line.
3. Building Height & Access
Two-story townhome: ladder access, 1 crew. Four-story apartment: boom lift or crane, fall protection plan, larger crew, longer schedule. Height adds 8-15% to labor.
4. Code Upgrades (Minnesota State Building Code)
If your roof was last replaced before 2015, expect ice-and-water shield to the warm wall plus upgraded ventilation. Code-driven add: $0.40-$0.80/sf.
5. Union vs. Open Shop Labor
Most quality commercial roofers in the Twin Cities run union (Local 96 Roofers, Local 322 Carpenters for siding/trim). Union labor adds 18-25% over open-shop but delivers documented training, safety, and crew stability — which matters when the warranty period is 20-30 years.
6. Tear-Off Disposal
Asphalt shingle disposal: $55-$75/ton tipping fee in metro Hennepin/Ramsey. EPDM/TPO disposal: special-handling $110-$160/ton. A 50-unit townhome community generates 35-55 tons of tear-off.
Insurance vs. Special Assessment: Two Funding Paths
Insurance Claim (Hail / Wind Damage)
If your community took hail in the last 12-24 months, your master policy likely covers replacement minus deductible. Typical HOA deductible in MN: 1-5% of insured value per building, often $10K-$50K per building. Start with our guide on whether HOA insurance covers roof replacement, then see our claim playbook for documenting damage before a carrier sends an adjuster who lowballs roof age.
Reserve Study + Special Assessment
No storm? You’re funding from reserves or assessing homeowners. A solid reserve study assumes 22-30 year shingle life and 20-25 year TPO life in Minnesota. Special assessments for a full roof replacement typically run $4,500-$12,000 per unit for townhomes, $8,000-$22,000 per unit for mid-rise condos.
How HOA Roofing Pro Builds a Board-Ready Bid
Plan-set + drone takeoff on every building, not “two roofs and we’ll estimate the rest”
Per-building line item so the board can phase if needed
Unit pricing for decking, fascia, soffit, ice-and-water — no surprise change orders
Three options: good (standard shingle), better (Class 4 hail), best (Class 4 + ventilation upgrade)
Manufacturer warranty paperwork drafted for the board package (GAF Golden Pledge, Carlisle Total Roof, etc.)
Insurance carrier coordination — we work directly with State Farm, Liberty Mutual, Travelers, American Family adjusters
MBE/DBE + union compliance documentation for any FHA/HUD-financed property
Red Flags in HOA Roofing Bids
No drone photos or per-building takeoff → contractor is guessing
“Allowance” for decking with no unit price → blank check on change orders
Single shingle option only → contractor isn’t thinking about your insurance discount
No warranty registration in the bid package → you’ll discover this at year 8 when a leak isn’t covered
Crew that does residential 80% of the time → multifamily code, height work, and association communication is a different game
Frequently Asked Questions
How long does an HOA roof replacement take?
A 4-building, 50-unit townhome community: 4-6 weeks weather permitting (see our multi-family roof replacement process guide for the full timeline). A 3-story 80-unit apartment: 3-5 weeks for a TPO replacement.
Do we need to vote unanimously?
No. Most MN HOA bylaws require simple majority of the board for replacement of an existing capital asset. New construction or upgraded materials beyond like-kind may require homeowner vote. Read our board vote process guide.
Can we get bids without committing?
Yes. HOA Roofing Pro provides a free no-obligation board-ready bid package including drone roof report, takeoff, three pricing options, and warranty info — typically 7-10 business days from site visit.